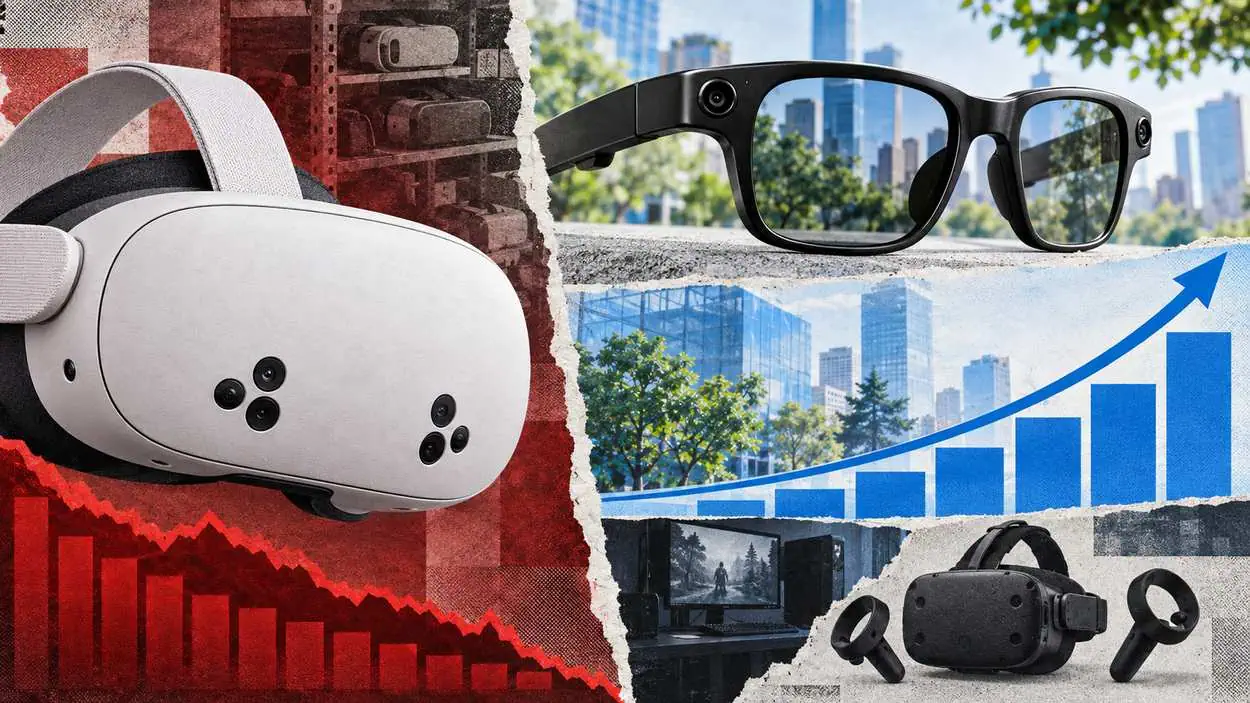




Worldwide XR device shipments grew 41.6% in 2025 to 14.5 million units. Almost none of that growth came from virtual reality headsets. IDC expected mixed and virtual reality headset shipments to decline 42.8% in 2025, while the rest of the XR market grew 211.2%.
Meta sits at the center of both halves of that split. It held 69.2% of the smart glasses and display-equipped eyewear market in Q1 2026, while its own VR division absorbed an operating loss of $4,619 million in the second quarter of 2026. The figures below separate the headset market from the eyewear market now carrying it.
Key Takeaways
- XR device shipments rose 41.6% in 2025 to 14.5 million units, while mixed and virtual reality headsets alone were set to fall 42.8%.
- Meta held 69.2% of the combined smart glasses and ARVR eyewear market in Q1 2026.
- Reality Labs generated $431 million in revenue in Q2 2026 against an operating loss of $4,619 million.
- Meta Quest 2 led Steam-connected headsets at 26.97% in August 2026, ahead of Quest 3 at 26.01%.
- Spending on AR/VR apps, services and related technologies rose 19.7% in 2025 to nearly $12 billion worldwide.
- Mixed reality shipments are projected to reach 15.2 million units by 2029, up from 3.3 million in 2025.
- Meta removed the Horizon Worlds app from Quest after June 15, 2026, ending Worlds availability in VR.
Editor’s Choice
- Display-less smart glasses shipments jumped 167% year over year in Q1 2026, reaching approximately 2.25 million units in a single quarter.
- Eyewear with displays grew 86% year over year in Q1 2026.
- Reality Labs’ operating loss reached $8,647 million across the first six months of 2026.
- Meta captured 50.8% of the AR/VR headset market in Q1 2025, up from 36.2% a year earlier.
- Valve’s Index held 11.07% of Steam-connected headsets in August 2026, against 2.24% for Sony’s PS VR2.
- PwC found VR trainees were up to 275% more confident to act on what they learned after training.
- IDC expects AR/VR hardware volumes to reach 43.1 million units in 2029.
Global XR And VR Device Shipments
Headline volume figures diverge depending on which IDC tracker you read, because the trackers overlap. The combined XR view counts headsets and glasses together, and that is the view showing growth.
- XR device shipments, headsets and glasses combined, grew 41.6% in 2025 to 14.5 million units.
- AR/VR headsets plus display-less smart glasses were expected to grow 39.2% in 2025, with volumes reaching 14.3 million units.
- Mixed reality shipments stood at 3.3 million units in 2025, with extended reality glasses at 2.2 million.
- Display-less smart glasses shipped approximately 2.25 million units in Q1 2026 alone.
| Category | Shipments (million units) | Period |
|---|---|---|
| XR devices, headsets and glasses | 14.5 | Full-year 2025 |
| AR/VR headsets plus display-less smart glasses | 14.3 | Full-year 2025 |
| Mixed reality headsets | 3.3 | Full-year 2025 |
| Display-less smart glasses | 2.25 | Q1 2026 |
| Extended reality glasses | 2.2 | Full-year 2025 |
Source: IDC Worldwide Quarterly AR/VR Headset Tracker and Worldwide Quarterly Wearable Device Tracker, 2025-2026
By the numbers: One quarter of display-less smart glasses shipments equals 15.5% of the entire XR device volume recorded across all of 2025. That single ratio is the cleanest summary of the category’s shift. A form factor with no display and no controllers now ships in a single quarter at a pace the entire XR category needed a full year to reach.
The glasses line is the one worth holding onto. Shipment data for AR technology shows the same eyewear-led direction across the wider category.
Vendor Market Share Across XR And Smart Glasses
Meta’s lead in the combined eyewear market is not a narrow one. IDC put the company at 69.2% market share in Q1 2026, built on its Ray-Ban partnership with EssilorLuxottica, with the rest of the field fragmented well below it.
- RayNeo took 3.4% share on lower-cost display glasses, with Xiaomi at 3.1% driven primarily by China shipments.
- Viture ranked fourth at 2.5% share after expanding into US retail, and XREAL rounded out the top five at 2.0%.
- The long tail of Chinese and global brands accounted for 19.8% collectively.
A share that size in a category this young is a head start rather than a moat. The open question is how long one vendor can set a category’s product expectations alone.

Recent Developments
- July 29, 2026: Meta reported Reality Labs revenue of $431 million and an operating loss of $4,619 million for the quarter ended June 30, 2026.
- August 2026: Valve’s monthly survey put Meta Quest 2 at 26.97% of Steam-connected headsets and Quest 3 at 26.01%.
- June 15, 2026: IDC reported display-less smart glasses up 167% year over year in Q1 2026 and eyewear with displays up 86%.
- June 15, 2026: Meta ended Horizon Worlds availability in VR, and the Horizon Worlds app was removed from Quest after that date.
- March 31, 2026: Meta withdrew Horizon-specific Meta Horizon Plus perks, including Meta Credits, digital clothing and avatars, from the subscription.
- 2026: Meta told developers it had separated the Quest VR platform from the Worlds platform and right-sized its Reality Labs investment.
Meta Reality Labs Revenue And Operating Losses
Reality Labs is the only place in public accounts where the cost of building this market is itemized, and its lines show revenue rising while losses hold near record levels. Revenue for Meta’s hardware segment came in at $431 million, against $370 million in the same quarter of 2025.
- The segment’s Q2 operating loss widened to $4,619 million from $4,530 million a year earlier.
- Across the first six months of 2026, the loss totaled $8,647 million, against $8,739 million in the prior-year period, which makes the half-year loss $92 million narrower.
- Segment revenue grew 16.5% year over year, yet Reality Labs still contributed only 0.7% of Meta’s total quarterly revenue.
- Backing the Q2 figure out of the half-year total puts the Q1 2026 operating loss at $4,028 million.
| Segment line ($ million) | Q2 2025 | Q2 2026 |
|---|---|---|
| Total revenue | 47,516 | 60,801 |
| Family of Apps revenue | 47,146 | 60,370 |
| Reality Labs revenue | 370 | 431 |
| Reality Labs operating loss | 4,530 | 4,619 |
| Total income from operations | 20,441 | 18,775 |
Source: Meta Platforms second-quarter 2026 earnings release, July 2026
The composition of that revenue line matters more than its size. A segment whose sales rise while headset shipments slide across the market has already redirected its spending.
SteamVR Headset Share By Device
Valve’s monthly hardware survey is the only public measurement of which headsets are actually connected and in use rather than merely sold, and it runs on a different basis from any shipment tracker. Participation is optional and anonymous, covering headsets connected to Steam during the survey month across Windows, Mac and Linux.
- Meta Quest 2 led at 26.97% in August 2026, with Quest 3 at 26.01% and Quest 3S at 11.50%.
- Valve’s own Index held 11.07%, ahead of Pico 4 at 4.48% and Oculus Rift S at 3.39%.
- HTC Vive sat at 2.39%, Sony PS VR2 at 2.24% and Windows Mixed Reality at 2.08%.
- Headsets outside the named list accounted for 9.87% of the total.
Why it matters: Meta’s Quest and Oculus devices together hold 67.87% of Steam-connected headsets, roughly 6.1 times the share of Valve’s own Index. A PC VR developer therefore builds for one vendor’s tracking, controllers and runtime, and the platform risk that follows never appears in a shipment table.
Meta’s Quest Family Concentration On SteamVR
Quest and Oculus devices occupy most of the named rows in Valve’s survey. The combined Quest 2, Quest 3, Quest 3S and Rift S share comes to 67.87% of Steam-connected headsets.
- Valve’s Index at 11.07% still holds 4.9 times the share of Sony’s PS VR2.
- Every non-Meta-named headset combined, from Index down through Windows Mixed Reality, reaches 22.26%.
Concentration at that level is a content-economics problem before it is a competition problem. The same dynamic on fixed hardware appears in console market share statistics, where concentration shapes which titles get made. The PC side of that comparison rests on discrete graphics supply, a market whose scale is visible in Nvidia workforce data.
AR/VR Headset Share Before The Glasses Shift
The headset-only market looked materially different a year earlier, before display-less glasses were folded into the headline numbers. IDC’s Q1 2025 cut recorded the global AR/VR headset market growing 18.1% year over year, led by Meta at 50.8%.
- Meta’s headset share climbed to 50.8% in Q1 2025 from 36.2% a year earlier, on 65.9% unit growth.
- XREAL took second at 12.1%, with ByteDance at 9.4%, Viture at 6.2% and TCL at 4.2%.
- Three of the top five vendors specialized in optical see-through glasses, collectively capturing 22.5% of the market for the first time.
- Sony and Apple were absent from the top rankings that quarter, as channels maintained healthy inventory of their products.
XR Category Forecasts Through 2029
IDC splits its long-range forecast into separate device classes, and mixed reality is the class absorbing the VR headset makers who pivoted.
- Mixed reality shipments are projected to grow from 3.3 million units in 2025 to over 15.2 million units by 2029.
- Extended reality glasses are expected to rise from 2.2 million to 8.6 million units over the same period.
- Augmented reality will see steadier growth, reaching 457,000 units by 2029.
- On the wider tracker that includes display-less glasses, hardware volumes reach 43.1 million in 2029 at a 31.8% compound annual growth rate.
IDC’s own framing of the rebound is worth repeating: MR/VR headsets are projected to rebound in 2026 with the launch of new devices, though their appeal will remain largely limited to gamers and businesses focused on design, training and collaboration.
Growth Rates By XR Category In 2025
Year-over-year change is where the split between headsets and glasses becomes unambiguous. One category contracted while every other line grew, the glasses-led lines by triple digits and the blended XR totals by double.
- Mixed and virtual reality headset shipments were expected to decline 42.8% in 2025, while the rest of the XR market grew 211.2%.
- Display-less smart glasses grew 247.5% during 2025, driven by smart glasses such as Meta’s Ray-Bans.
- XR glasses are forecast to grow at a 29.3% compound annual growth rate from 2025 to 2029.
| Category | 2025 shipment change (%) |
|---|---|
| Display-less smart glasses | 247.5 |
| XR market excluding MR and VR headsets | 211.2 |
| XR devices overall | 41.6 |
| AR/VR headsets plus smart glasses combined | 39.2 |
| Mixed and virtual reality headsets | -42.8 |
Source: IDC Worldwide Quarterly AR/VR Headset Tracker and Wearable Device Tracker, 2025
IDC’s earlier read pointed the other way. In June 2025, the firm expected a strong rebound in 2026 with 87% growth, ultimately surpassing the pandemic-era peak of 11.2 million units. Six months later, the same tracker described a glasses-led market and a headset category in retreat, which is a useful reminder that the forecast line in any XR model moves faster than the installed hardware does.
VR Software And Services Spending
Content spending points to gaming as the dominant use of VR headsets. IDC put spending on apps, services and related technologies up 19.7% in 2025, to nearly $12 billion worldwide.
- Top-grossing titles in the first half of 2025 were Animal Company, Beat Saber and Gorilla Tag.
- Measured by hours of use rather than revenue, YouTube led the pack.
| Spending or volume line | Figure | Period |
|---|---|---|
| AR/VR apps, services and related technologies | nearly $12 billion | Full-year 2025 |
| Growth in that spending | 19.7% | Full-year 2025 |
| AR/VR hardware volumes | 43.1 million units | 2029 forecast |
| Hardware compound annual growth rate | 31.8% | 2025-2029 |
| XR glasses compound annual growth rate | 29.3% | 2025-2029 |
Source: IDC Worldwide Quarterly AR/VR Headset Tracker and Wearable Device Tracker, 2025-2029
That top-grossing list also explains the headset market’s ceiling: the highest-earning titles are social games, and the device most people reach for a social game is a phone. The same pattern shapes the hardware mix documented in PlayStation statistics.
VR In Corporate Training
Enterprise training is the non-gaming use case with the most published efficacy data behind it, though the strongest numbers predate the current hardware generation. PwC’s VR Soft Skills Training Efficacy Study compared classroom, e-learning and VR delivery of the same soft-skills course.
- Employees in VR courses could be trained up to four times faster, with two hours of classroom content possibly learned in only 30 minutes.
- Learners trained with VR were up to 275% more confident to act on what they learned, a 40% improvement over classroom and 35% over e-learning.
- V-learners felt 3.75 times more emotionally connected to the content than classroom learners and 2.3 times more connected than e-learners.
- VR-trained employees were up to four times more focused during training than their e-learning peers and 1.5 times more focused than classroom colleagues.
The focus finding is the one that travels furthest, because a headset removes the multitasking surface entirely. That makes it a blunt instrument against the attention patterns documented in social media attention span statistics. PwC’s adoption figure gives the demand side: its 2022 US Metaverse Survey found 51% of companies either integrating VR into strategy or already running it in at least one dedicated line of business, on a base of 1,004.
Both figures carry their age on their face, and they remain the best-documented numbers available. The adjacent question of which skills get retrained at all is covered in AI job loss statistics, and the same simulation-training argument recurs in healthcare.
Why Meta’s Share Reads Differently In Every Tracker
Meta’s market share appears as several different numbers across IDC publications, and the difference is scope rather than momentum. Each figure counts a different set of devices, so they do not form a trend line.
- Q1 2025 headsets only put Meta at 50.8%.
- Q2 2025 headsets plus display-less smart glasses put Meta at 60.6%.
- Q3 2025 XR devices, headsets and glasses combined, put Meta at 75.7% with its combined Quest and Ray-Ban lineup.
- Q1 2026 smart glasses plus display-equipped eyewear put Meta at 69.2%.
| Period | Meta share | IDC tracker scope |
|---|---|---|
| Q1 2025 | 50.8% | AR/VR headsets only |
| Q2 2025 | 60.6% | AR/VR headsets plus display-less smart glasses |
| Q3 2025 | 75.7% | XR devices, headsets and glasses combined |
| Q1 2026 | 69.2% | Smart glasses plus ARVR eyewear with displays |
Source: IDC Worldwide Quarterly AR/VR Headset Tracker and Worldwide Quarterly Wearable Device Tracker, 2025-2026
Stacking those four figures into one growth chart would report a definition change as a market move. Meta leads every cut of this market, and the cuts are not comparable to each other.
What Meta’s Platform Split Means For VR Content
Meta restructured its VR software strategy, and the change is documented on its own developer channel rather than inferred from shipments. The company said it was explicitly separating the Quest VR platform from the Worlds platform, doubling down on the VR developer ecosystem while shifting the focus of Worlds to be almost exclusively mobile.
- Meta acknowledged that the VR industry had not grown as much or as quickly as hoped, while stating it is still growing.
- The company said it had right-sized its Reality Labs investment and retains a roadmap of future VR headsets tailored to different audience segments.
- Horizon Worlds and Events stopped appearing in the Quest store by March 31, 2026, with the Horizon Worlds app removed from Quest after June 15, 2026.
- Hyperscape capture viewing moved out of Horizon Worlds by March 24, 2026.
Read against the segment accounts, the split is a cost decision described as a focus decision. Moving the social layer to phones leaves Quest as what the content spending already showed it to be.
Is the VR headset market shrinking?
The headset category is shrinking as a standalone segment while the wider XR market it belongs to grows. IDC expected mixed and virtual reality headset shipments to fall 42.8% in 2025 while the rest of the XR market grew 211.2%, and a separate IDC tracker forecast a 12% decline in total AR/VR headset shipments in 2025 on delayed product launches, before mixed and extended reality drive long-term expansion.
The nuance is that most of those headsets are being reclassified rather than abandoned. Mixed reality, the class most current headsets now fall into, is projected to grow to over 15.2 million units by 2029 from 3.3 million in 2025. The label is retreating faster than the hardware.
Which VR headset has the largest install base on Steam?
Meta Quest 2 has the largest measured share of Steam-connected headsets, at 26.97% in August 2026, with Quest 3 close behind at 26.01%. Valve’s survey covers headsets connected during the survey month, so it measures active use rather than cumulative sales, and no public source publishes cumulative install-base figures for these devices.
Across the whole named list, the Quest and Oculus family reaches 67.87%. Valve’s own Index remains the highest-placed non-Meta headset at 11.07%.
Conclusion
The defining figure for 2026 is the gap between two growth rates from the same tracker: XR devices up 41.6% in 2025 to 14.5 million units against mixed and virtual reality headsets down 42.8%. Meta funds both sides of that gap, absorbing an operating loss of $4,619 million in Q2 2026 on $431 million of Reality Labs revenue while holding 69.2% of the eyewear market in Q1 2026. On the install-base side, Valve’s August 2026 survey still shows Quest 2 leading Steam-connected headsets at 26.97%.
Neither headline usually written from this data holds. VR is not dead, because content spending rose and the mixed reality forecasts climb; and VR is not rebounding, because the growth sits in a glasses category most VR software cannot run on. Read the headset numbers and the eyewear numbers as two markets sharing one tracker.